



The direct fix-and-flip real estate investment strategy remains a primary vehicle for deploying institutional capital and capturing market spread. However, executing a profitable exit requires more than basic construction completion; it demands a precise calculation of capital velocity. In highly competitive seasonal windows, holding costs can quickly erode projected spreads.
Data highlights the shifting realities of asset monetization. While absolute transaction volume historically marks steady baselines, aggregate margins frequently fluctuate. For instance, national data points reveal periods where gross profit margins compressed by over 3% to 6% from previous cyclical peaks, driven largely by extended days on market (DOM). Every week, an asset sits idle on the market, carrying costs, including private money interest, insurance, taxes, and utility overhead, eat directly into the investor’s bottom line. Lingering properties inevitably lead to price reductions. To insulate capital and optimize returns during the high-velocity summer buying season, operators must transition from a construction mindset to an institutional disposition strategy.
Once physical rehabilitation is finalized, the asset must be positioned to justify its target valuation immediately upon hitting the Multiple Listing Service (MLS). Staging is not merely decorative; it is an algorithmic approach to maximizing perceived asset value and accelerating buyer disposition.
The core objective of staging is to accentuate high-value architectural features while neutralizing potential spatial liabilities. Operators must treat the property walkthrough as a physical underwriting process for the retail buyer.
| Visual Tactic | Investor ROI Impact |
|---|---|
| High-Output Lumens (3000K) | Eliminates dark spaces; maximizes perceived square footage. |
| Tactile Textile Texturing | Encourages psychological ownership and dwell time. |
| Dead-Space Monetization | Transforms dead zones (e.g., under stairs) into usable space. |
“Success in institutional real estate investing relies strictly on capital velocity and the efficiency of the underwriting process.”
Setting an asking price cannot rely on speculative intuition or sentimental valuation of the rehab work. Overpricing an asset causes it to stagnate, marking it with a historical digital footprint that invites low-ball opportunistic offers. Underpricing needlessly leaves investor equity on the table.
The baseline metric for asset pricing is the After-Repaired Value (ARV)—the definitive calculation of a property’s market worth post-rehabilitation.
To reverse-engineer a viable purchase, rehab, and exit lifecycle, institutional flippers deploy precise financial formulas. The foundational algorithm for calculating the maximum allowable offer price, which directly informs the final retail exit strategy, is structured as follows:
Maximum Offer Price = ARV − Estimated Repair Costs − Holding & Closing Costs − Target Net Profit
To establish an accurate ARV that withstands appraisal scrutiny during the retail buyer’s financing phase, operators must follow a strict three-tier verification process:
While direct-to-consumer marketing avenues exist, leveraging an experienced, hyper-local real estate agent remains a critical component for accelerating capital velocity. Attempting to manage the disposition process independently frequently results in systemic administrative delays and subpar market exposure.
An elite transactional agent provides institutional-grade infrastructure that individual investment firms rarely maintain in-house:
Avoid selecting an agent based on personal relationships or superficial internet search visibility. Interview prospective listing brokers with an emphasis on performance metrics: demand data on their average days on market (DOM) for flipped assets, their list-to-sale price ratios within the specific submarket, and their direct experience navigating fast-moving summer sales environments.
The summer real estate market introduces distinct macroeconomic dynamics that agile investment operators can leverage to maximize deal velocity. Understanding consumer psychology and seasonal logistical timelines allows flippers to structure their marketing campaigns for maximum impact.
A primary catalyst for summer buyer demand is the rigid timeline dictated by academic calendars. Families trading up or relocating seek to execute purchase contracts, clear title underwriting, and physically transition into the new property before the upcoming school year begins. This hard deadline injects a high level of urgency into the retail buyer pool, translating into faster contract signings and a higher likelihood of clean, non-contingent offers.
The summer solstice provides extended daylight hours, widening the daily window for property showings and twilight open houses. Properties show better under natural sunlight, which highlights premium exterior finishes, fresh landscaping, and new architectural siding.
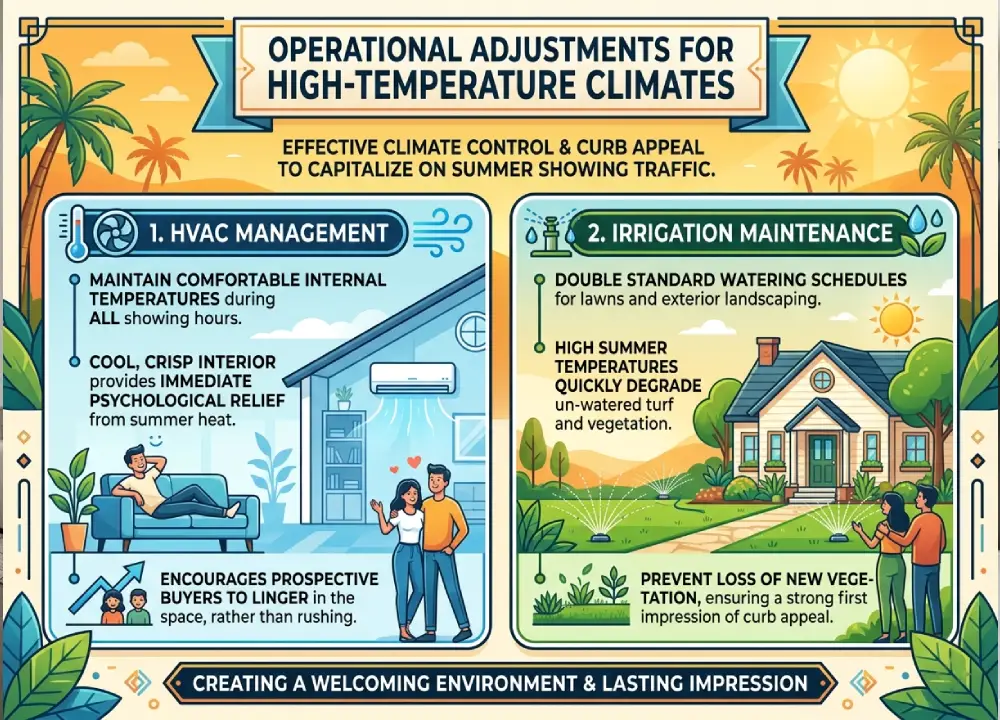
To capitalize effectively on summer showing traffic, operators must actively manage the property’s climate control and curb appeal:
Successfully closing a summer fix-and-flip transaction unlocks liquidity that must be efficiently redeployed to protect yield momentum. Rather than treating an asset sale as an isolated event, sophisticated operators view the closing table as the launchpad for their next acquisition pipeline.
By scaling your operational framework and applying systematic staging, data-driven ARV pricing, and seasonal marketing strategies, you transform individual property flips into a highly repeatable business model.
To maintain continuous capital velocity when transitioning from a successful summer exit into a new acquisition, real estate operators require access to flexible, non-bank financing solutions. Securing your next value-add asset demands institutional speed that conventional banking institutions cannot match. Partnering with a dedicated private money lender ensures your capital pipeline remains uninterrupted through every seasonal market cycle.
Ready to maximize your capital velocity on your next fix-and-flip project? Don’t let seasonal market windows close while waiting on traditional bank financing. Partner with a dedicated private money lender who understands institutional speed. Apply for Financing with Gauntlet Funding Today.
Market Data: According to data from the ATTOM U.S. Home Flipping Report, the average gross flipping profit yielded a 27.5% return on investment nationwide in recent quarters, highlighting the critical importance of keeping holding costs low to maximize capital velocity.
Financial Disclaimer
The information provided is for educational and informational purposes only. The content on this website is not intended to be a substitute for personalized financial advice. Please consult a certified financial professional before making any investment decisions or financial plans. Any financial information presented is for general informational purposes and does not constitute financial or investment advice.








