

As the 2026 real estate market continues to evolve, savvy investors are keeping a close watch on shifting financial landscapes. For those looking to secure property quickly, understanding the current environment for Hard Money Lenders is essential to maintaining a competitive edge. Unlike traditional financing, hard money offers the speed and flexibility necessary to close deals in a matter of days rather than months.
In this guide, we break down what is driving hard money lenders today and what you should anticipate regarding rates, fees, and overall borrowing costs as you scale your portfolio this year.
Real estate investment in 2026 has been defined by a “return to fundamentals.” While traditional mortgage rates have seen some stabilization, Morgan Stanley analysts suggest that while the first half of the year may offer some easing, volatility remains a factor for the latter half. For private lending, this means hard money interest rates are staying in a range that reflects both the increased demand for quick capital and the specialized nature of asset-based lending.
Generally, investors can expect hard money interest rates in 2026 to hover between 9.5% and 12.5%. These rates are primarily influenced by:
Because hard money is designed for short-term use (typically 6 to 24 months), the higher interest rate is often offset by the profit generated through rapid project completion and asset turnover.

When calculating the true cost of a loan, the interest rate is only part of the equation. Investors must account for lender fees that are standard in the private money industry. These fees cover the risk assessment, underwriting, and rapid processing that traditional banks simply cannot provide.
Most Hard Money Lenders charge “points” at closing. One point is equal to 1% of the total loan amount. In 2026, the industry standard remains between 1.5 and 3 points. If you are securing a $400,000 loan, expect to pay between $6,000 and $12,000 in origination fees.
Beyond the interest and points, you should budget for the following common expenses:
“As liquidity returns to North American real estate markets in 2026, private equity and local investors are becoming more prominent sources of funding, acting as a counterbalance to traditional institutions.”
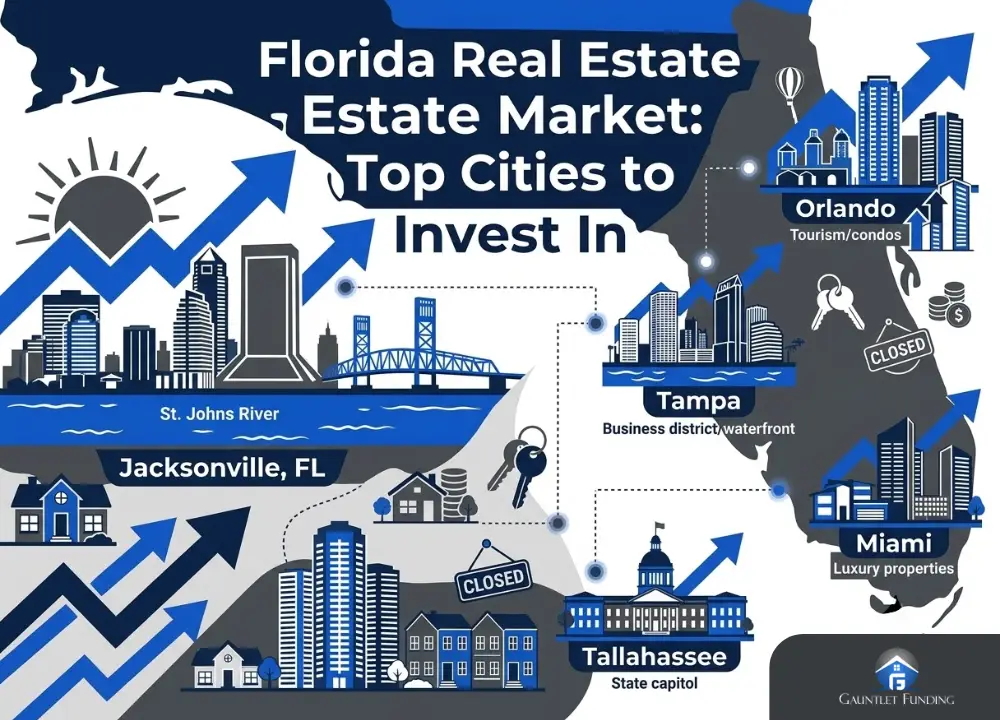
At Gauntlet Funding, we emphasize that every deal is unique. While market averages provide a baseline, your specific project details will dictate the final terms. Direct lenders look for “deal viability” rather than just a credit score. This flexibility is why bridge loans and fix and flip financing continue to be the preferred tools for developers in high-competition areas like New York and Florida.
Residential fix and flip properties generally carry different risk profiles than ground-up new construction or multi-family bridge loans. A property in a high-demand urban corridor may command better terms due to the ease of resale (exit strategy) compared to a rural property with fewer comparable sales.
New investors might face slightly higher rates as they build their portfolio. However, once you have three to five successful exits under your belt, you gain significant leverage to negotiate lower points and better draw schedules.
The most successful investors in 2026 are those who view real estate loan costs as a tool rather than a hurdle. If a hard money loan allows you to secure a property at a $50,000 discount because you can close in 7 days, the $10,000 in interest and fees becomes a highly profitable investment.
When vetting lenders this year, prioritize transparency. A direct lender should be able to provide a clear term sheet without hidden “junk fees” that appear at the last minute. Transparency in lending is the foundation of a long-term partnership that helps you scale your real estate business regardless of market fluctuations.
2026 Market Insight: The United States digital and private lending market is estimated to grow to $339.22 billion in 2026, reflecting a significant shift toward alternative financing for business and real estate needs.
Financial Disclaimer
The information provided is for educational and informational purposes only. The content on this website is not intended to be a substitute for personalized financial advice. Please consult a certified financial professional before making any investment decisions or financial plans. Any financial information presented is for general informational purposes and does not constitute financial or investment advice.