


New York property investors can make a lot of money by renovating homes and then selling them at the new value. However, this process takes capital. Fortunately, fix and flip loans are specifically designed for this purpose.
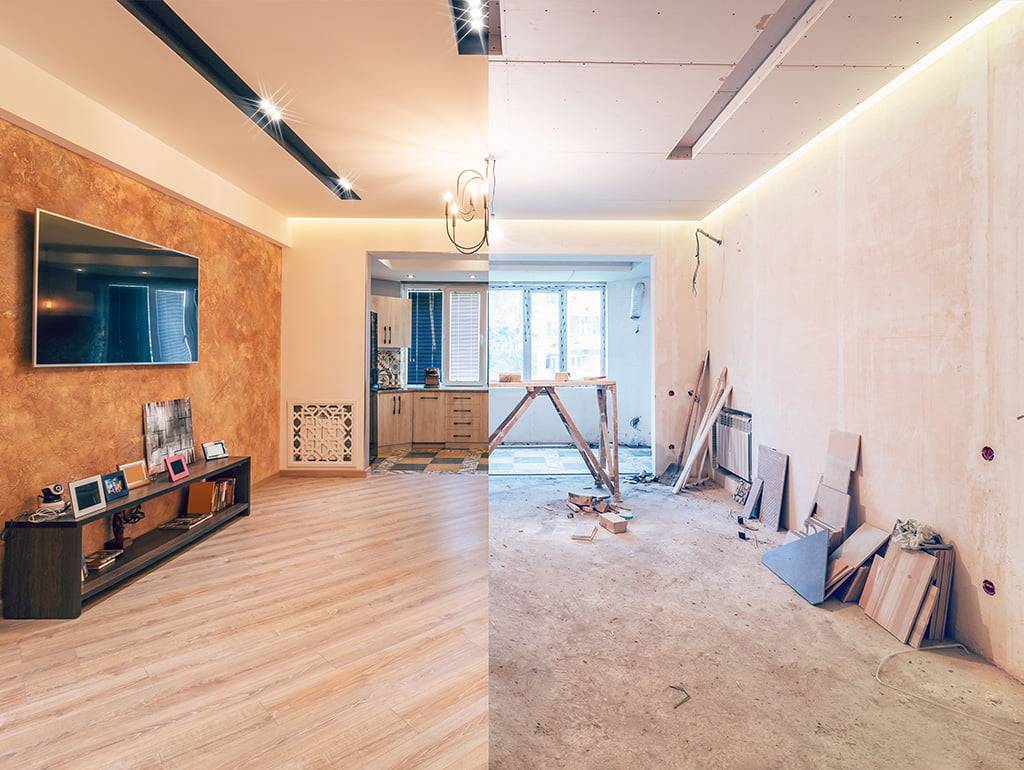 A fix and flip loan is a specific type of hard money financing, which is lending provided outside of traditional financial institutions such as banks and credit unions. Since these third-party lenders don’t have to adhere to the same regulations as banks, they can offer a wider variety of loans with greater leeway.
How do you know if private money lending in New York is right for you? This financing works best for property investors who intend to quickly sell a property after renovation. Of course, there are other lending options, so it’s essential to consider the pros and cons of fix and flip loans before applying.
The pros of fix and flip loans vastly outweigh the cons for many people. In fact, hard money financing is sometimes the only option for property investment.
Property investors often have a lot of irons in the fire, which means simultaneous loans to fund their projects. Unfortunately, this debt may disqualify them for good interest rates or loan approval, even though these individuals are turning a profit.
The approval criteria are less stringently regulated for third-party lenders, which means they can provide funding where banks can’t. They may even offer financing programs for applicants with poor credit histories or past loan rejections.
If you plan to fix and flip a house, you need to cover several expenses:
A fix and flip loan lets you spend the funds on all of the above and more. For example, if you encounter unexpected repairs, you can use this financing to care for them.
Traditional bank loans require mountains of paperwork detailing your financial dealings. However, a fix and flip loan can be approved based on the value of the purchased property. Most third-party lenders use a loan-to-value ratio to determine the loan amount.
For example, a lender may offer 75% LTV of a home’s value. Focusing on property value is a boon to debt or poor credit history investors. If the real estate value covers the principal and other requirements, they may get approved despite a lack of record.
Since there’s less paperwork, fix and flip loans get approved at an expedited rate. Mortgages can take as long as 45 days to process because banks need to verify every document provided. In contrast, you can get funding from a fix and flip loan within two weeks. This short time frame is essential if you’re trying to negotiate with a seller or snatch up prime real estate.
Yes, short terms can be a benefit as well as a drawback. Most fix and flip loan terms don’t exceed two years, compared to the 30 years most mortgages last. Since property investors aim to sell their renovated real estate, they don’t have to worry about paying off such a large amount within such a short time. In fact, a short term is beneficial in this industry since it means borrowers won’t have as much debt in their name when they apply for future financing.
Every type of lending has drawbacks. As a borrower, you need to consider whether they outweigh the benefits. Many options for private money lending in New York have similar caveats.
Compared to traditional bank loans, fix and flip loans have higher interest rates. Lenders charge higher rates because they’re taking on more risk, so they need to ensure the transaction is worth it.
However, higher interest rates may not pose too much of an issue with fix and flip loans because the loan terms are very short. Most property investors plan to sell real estate as fast as possible and pay back the loan before too much interest accrues.
To counter the higher risk, lenders may also require you to place a large down payment on the property. If you don’t have the funds handy, this requirement may stretch your resources.
Fix and flip loans are short-term financing, which means you could be expected to pay back the principal (with interest) in as little as a year. If the housing market isn’t in your favor, this could put you in a tight spot.
Are you looking for private money lending in New York? Gauntlet Funding can help you find the perfect loan. For more information, visit us online or call (631) 465-2161.
Looking for private money lending in New York? Gauntlet Funding helps investors find the right fix and flip loan for every project. Contact our experts today to secure fast, flexible funding and start your next profitable renovation.
Investors can increase profitability by understanding market trends and project budgeting. According to RealtyTrac, homes flipped in New York in 2024 saw an average ROI of 38% when proper planning and funding were applied. Using a fix and flip loan strategically ensures investors can access high-demand neighborhoods without tying up personal capital.
Another consideration is partnering with lenders experienced in New York’s competitive market. Expert lenders can advise on the most profitable renovation projects, provide realistic timelines, and offer flexible funding structures. Properly leveraging fix-and-flip loans can be the difference between a profitable flip and financial stress.
For example, investing in cosmetic upgrades like kitchens and bathrooms yields higher returns than larger structural renovations. Investors using hard money financing often see faster project turnaround and quicker ROI due to the short approval timelines.
“In the first quarter of 2022, 10% of U.S. homes sold were flipped, the highest rate since 2000, indicating a robust market for fix-and-flip investments.”
— Rick Sharga, Executive Vice President of Market Intelligence, ATTOM (axios.com)
Ready to take your New York property investment to the next level? Explore our fix and flip loan options and get approved in as little as two weeks. Don’t wait. Turn your renovation plans into profits today!
Financial Disclaimer
The information provided is for educational and informational purposes only. The content on this website is not intended to be a substitute for personalized financial advice. Please consult a certified financial professional before making any investment decisions or financial plans. Any financial information presented is for general informational purposes and does not constitute financial or investment advice.

Fix and Flip Loans: Learn If This Financing Is Right for You | Gauntlet Funding – Melville, NY









