


For real estate investors, the beauty of DSCR loans lies in their simplicity. Unlike traditional mortgages that require mountains of tax returns, W-2s, and personal pay stubs, these specialized investment loans focus primarily on one metric: the property’s ability to pay for itself. However, while the concept of income-based lending sounds straightforward, the process of property income verification is highly structured. Lenders do not just take an investor’s word for what a property will earn; they use a combination of verified documents and professional appraisals to ensure the numbers add up.
Understanding how a private money lender calculates your Debt Service Coverage Ratio is the first step toward securing a successful investment. By mastering the nuances of market rent analysis and knowing which lease agreements carry the most weight, you can position your deal for the best possible leverage. At Gauntlet Funding, we work with investors to clarify these technical underwriting steps early, ensuring a fast, flexible, and transparent closing process without personal underwriting red tape.
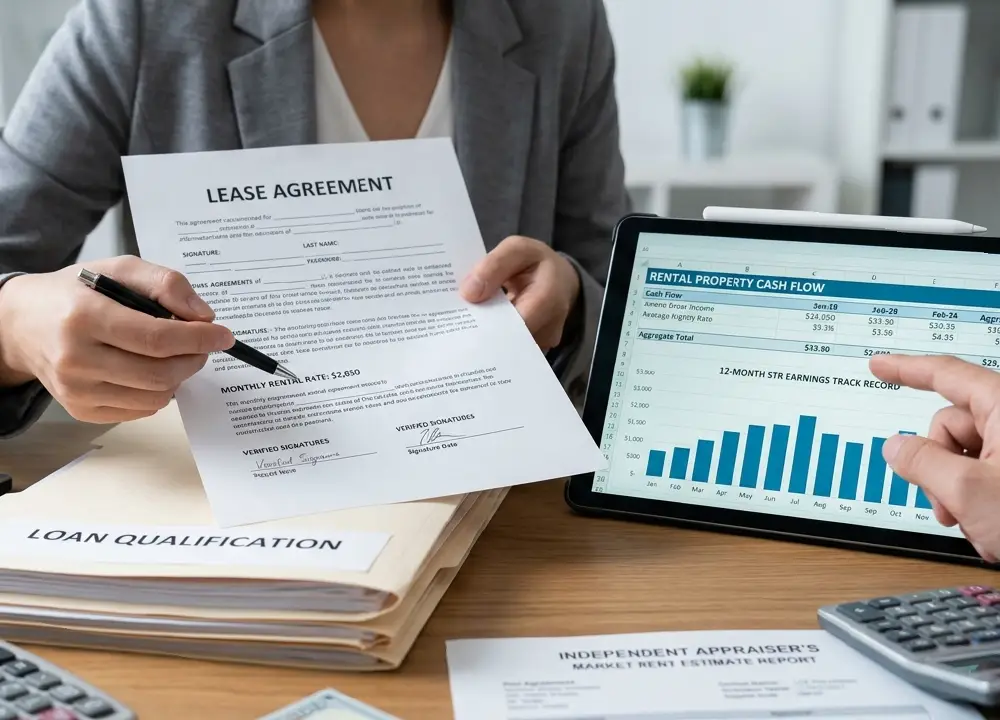
When you apply for a debt service coverage ratio loan, the underwriter’s goal is to determine the gross rental income of the asset. This figure serves as the numerator in the ultimate ratio calculation. But how do lenders arrive at that number safely? It typically comes down to two main sources: an existing executed lease and an independent appraiser’s market rent estimate.
If you are looking to refinance an existing asset or purchase a property that is already occupied by tenants, lease agreements serve as your primary evidence of income. Underwriters look for fully executed contracts that clearly state the monthly rental rate, the remaining lease term, and the verified signatures of all parties involved. In most cases, lenders will utilize the lesser of the actual lease amount or the appraised market rent to remain conservative. If your current lease is significantly higher than the local neighborhood average, you may be asked to provide additional proof of consistent on-time payments, such as consecutive bank statements or a certified property rent roll, to justify using that higher figure.
For investors focused on vacation rentals, short-term corporate stays, or Airbnbs, the verification process looks slightly different. Since these properties do not have long-term lease agreements in place, lenders often require a 12-month history of structural earnings directly from a professional booking platform like Airbnb or VRBO, or a specialized third-party management report. This historical track record helps prove that the property’s seasonal peaks and valleys still result in a strong, stable annual coverage ratio during loan qualification.
Every commercial or residential investor asset requires a professional appraisal, but the evaluation is not just about the final sales price. Lenders also order a Comparable Rent Schedule, most commonly known as Fannie Mae Form 1007 for single-family homes or Form 1025 for multi-unit properties. This market rent analysis is critical because it provides a completely unbiased look at what similar properties in the immediate local radius are actually renting for today.
“Real estate investors bought a record 26.1% of low-priced U.S. homes that sold, marking the highest share on record as individual buyers backed away due to elevated borrowing costs.”
— Redfin Market Analysis: Investor Home Purchases Report
The independent appraiser looks at comparable properties within a narrow geographic radius, adjusting the figures for specific factors like overall property condition, total square footage, and unique modern amenities such as a finished basement or updated kitchens. If the appraiser’s market rent estimate comes in lower than your written lease, it can instantly drop your calculated ratio and potentially affect your interest rate or maximum loan-to-value ratio. This is exactly why it is vital to research local market data before committing to a purchase contract.
Once the lender has thoroughly verified the gross income, they compare it against the total debt service. This includes the full monthly PITIA: Principal, Interest, Taxes, Insurance, and any applicable Homeowners Association fees. For real estate professionals looking for competitive real estate investment loans, the target ratio for premier pricing is usually 1.20 or higher, meaning the property generates at least 20% more monthly income than the baseline cost of the debt service.
If the market rent analysis results in a ratio below 1.0, the property is considered non-cash flowing in the eyes of an underwriter. While some niche programs allow for low-ratio or no-ratio structures, these typically require a larger cash down payment or a higher borrower credit score to offset the increased operational risk. Experienced investors often use these low-ratio situations as a clear strategic signal to renegotiate the purchase price with the seller or look for structural ways to increase the property’s value before closing the transaction.
Meeting the absolute DSCR ratio requirements is just the first benchmark. The total strength of your ratio directly impacts your leverage options. A property with a strong 1.50 ratio will naturally qualify for higher leverage and lower interest rates compared to an asset sitting right at a 1.05 benchmark. Maximizing your rental property cash flow prior to underwriting ensures you walk away with the best possible commercial terms.
To ensure a smooth, quick property income verification process, investors should actively work to avoid these common underwriting mistakes:
Whether you are scaling a growing portfolio of single-family homes or moving aggressively into multi-family units, understanding these technical rules helps you act with the speed of a seasoned professional. By preparing your documentation and vetting your property’s rent potential ahead of time, you can navigate the underwriting process with total ease.
At Gauntlet Funding, we understand that every real estate deal is unique. We provide the institutional expertise and the direct capital to help you close quickly and efficiently. If you are ready to put your next investment property to work, contact our experienced team today to explore our customized financing solutions.
Financial Disclaimer
The information provided is for educational and informational purposes only. The content on this website is not intended to be a substitute for personalized financial advice. Please consult a certified financial professional before making any investment decisions or financial plans. Any financial information presented is for general informational purposes and does not constitute financial or investment advice.









