



If you invest in real estate, you already know that the best deals don’t wait around for a 45-day bank approval. Whether you’re bidding against cash buyers, working an off-market opportunity, or trying to close on a property before another investor does, financing speed can be the difference between winning a deal and watching it go to someone else.
That’s the problem hard money loans are built to solve. This guide covers what hard money loans are, how they actually work, why so many investors use hard money lenders instead of (or alongside) traditional banks, and, just as important, when a hard money loan is genuinely the right tool for your deal, and when it isn’t.
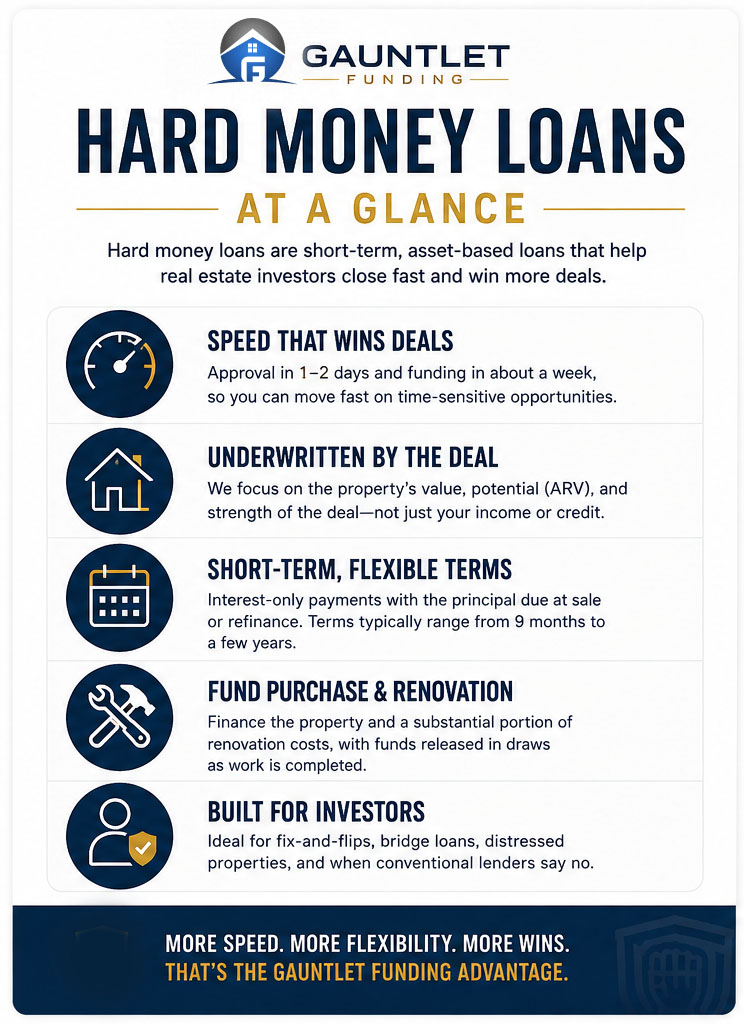
A hard money loan is a short-term, asset-based loan used primarily for real estate investment deals. Instead of underwriting a loan mainly around your income, tax returns, and personal credit history the way a conventional mortgage lender does, a hard money lender underwrites around the property itself: its current value, its after-repair value (ARV), and the overall strength of the deal.
Hard money loans are typically funded by private lenders or private lending companies, rather than banks or credit unions. Because the loan is secured by the property and sized to its value and potential, rather than the borrower’s entire financial picture, hard money lenders can move much faster than traditional lenders. They’re often able to work with borrowers who wouldn’t qualify for a conventional mortgage, including many investors who prefer to close in the name of an LLC or other business entity.
You’ll sometimes see hard money lending referred to as asset-based lending or private real estate lending. All three terms describe the same core idea: financing decisions built around the deal, not just the borrower’s paperwork.
While every lender structures things a little differently, most hard money loans share the same basic framework:
Hard money loans cost more than conventional financing, so investors use them deliberately, not by default. Here’s what they’re buying with that extra cost:
This is the number one reason investors turn to hard money. A bank can take up to 45 days to approve a loan. Many hard money lenders can approve a deal in one to two days and fund within about a week. Fast enough to compete for time-sensitive acquisitions and off-market opportunities.
Traditional lenders evaluate a property largely as-is and can be reluctant to lend on anything that needs significant work. Hard money lenders are set up to evaluate a property’s potential (its after-repair value and the strength of the investment thesis), which is exactly the kind of deal a bank is most likely to pass on.
Because hard money loans are designed for short-term projects, they’re structured without the 15- to 30-year assumptions baked into a conventional mortgage. Many hard money lenders also don’t charge prepayment penalties, while banks often apply exit fees on the remaining balance if you pay off a loan early, a meaningful difference for an investor planning to sell or refinance quickly.
Beyond the purchase price, many hard money lenders will also finance a portion of renovation expenses, disbursed in draws as work is completed. That means one loan can cover both the acquisition and the rehab, instead of stacking separate financing for each.
Distressed properties, deals with a short due-diligence window, and borrowers using an LLC or other entity to hold title can all be difficult to finance conventionally. Hard money lenders are built around exactly these situations.
Hard money isn’t the right financing for every deal; it’s a tool for specific situations. Here’s when it tends to make the most sense:
Because hard money loans trade underwriting speed and flexibility for the risk the lender is taking on, they typically carry higher interest rates and additional points compared with a conventional mortgage. Exact pricing varies by lender and by deal, based on factors like loan-to-value, the borrower’s experience, and the strength of the exit strategy, so it’s worth comparing more than one lender before you commit.
When you apply, most hard money lenders will ask for:
Hard money loans overlap with a few other financing types that investors use. A quick breakdown of how they differ:
Hard money vs. bank loans: banks are slower and stricter but cheaper over time. Hard money trades the cost for speed and flexibility.
Hard money vs. DSCR loans: DSCR loans qualify borrowers based on a property’s rental income and are built for longer-term rental holds. Hard money is built for short-term acquisition, rehab, and turnaround. Learn more: DSCR Loans for Real Estate Investors.
Hard money vs. bridge loans: bridge loans are a close cousin of hard money; both are short-term and asset-based, but bridge loans are used specifically to “bridge” the gap between a purchase and a planned refinance or sale. Read more: Bridge Loans for Real Estate Investors.
Not all hard money lenders operate the same way, and the wrong one can cost you time and money on a deal where both are already tight. Look for clear terms, transparent fees, a track record of closing on time, and no prepayment penalty.
For a full checklist of what to ask and the red flags to watch for, see Gauntlet Funding’s guide: How to Choose a Hard Money Lender.
Hard money lenders place more weight on the property and the deal than on credit score, so requirements are typically more flexible than a bank’s, though standards still vary from lender to lender.
Many hard money lenders can approve a loan in one to two days and fund within about a week. Some can move even faster when a deal is time-sensitive.
No. Fix-and-flip is the most common use, but hard money loans are also used for bridge financing, land acquisition, and ground-up or value-add construction.
Most do. The exact amount depends on the lender, the loan-to-value, and the deal itself.
The terms are often used interchangeably. Both describe financing from non-bank, private capital sources that underwrite primarily around the property and the deal.
Gauntlet Funding is a private, asset-based lender built for real estate investors, with fast approvals, transparent terms, and no prepayment penalties. If you have a deal on the table and need financing that can move at your pace, reach out and let’s talk through your project.
Financial Disclaimer: The information provided is for educational and informational purposes only. The content on this website is not intended to be a substitute for personalized financial advice. Please consult a certified financial professional before making any investment decisions or financial plans. Any financial information presented is for general informational purposes and does not constitute financial or investment advice.







